Funding studios
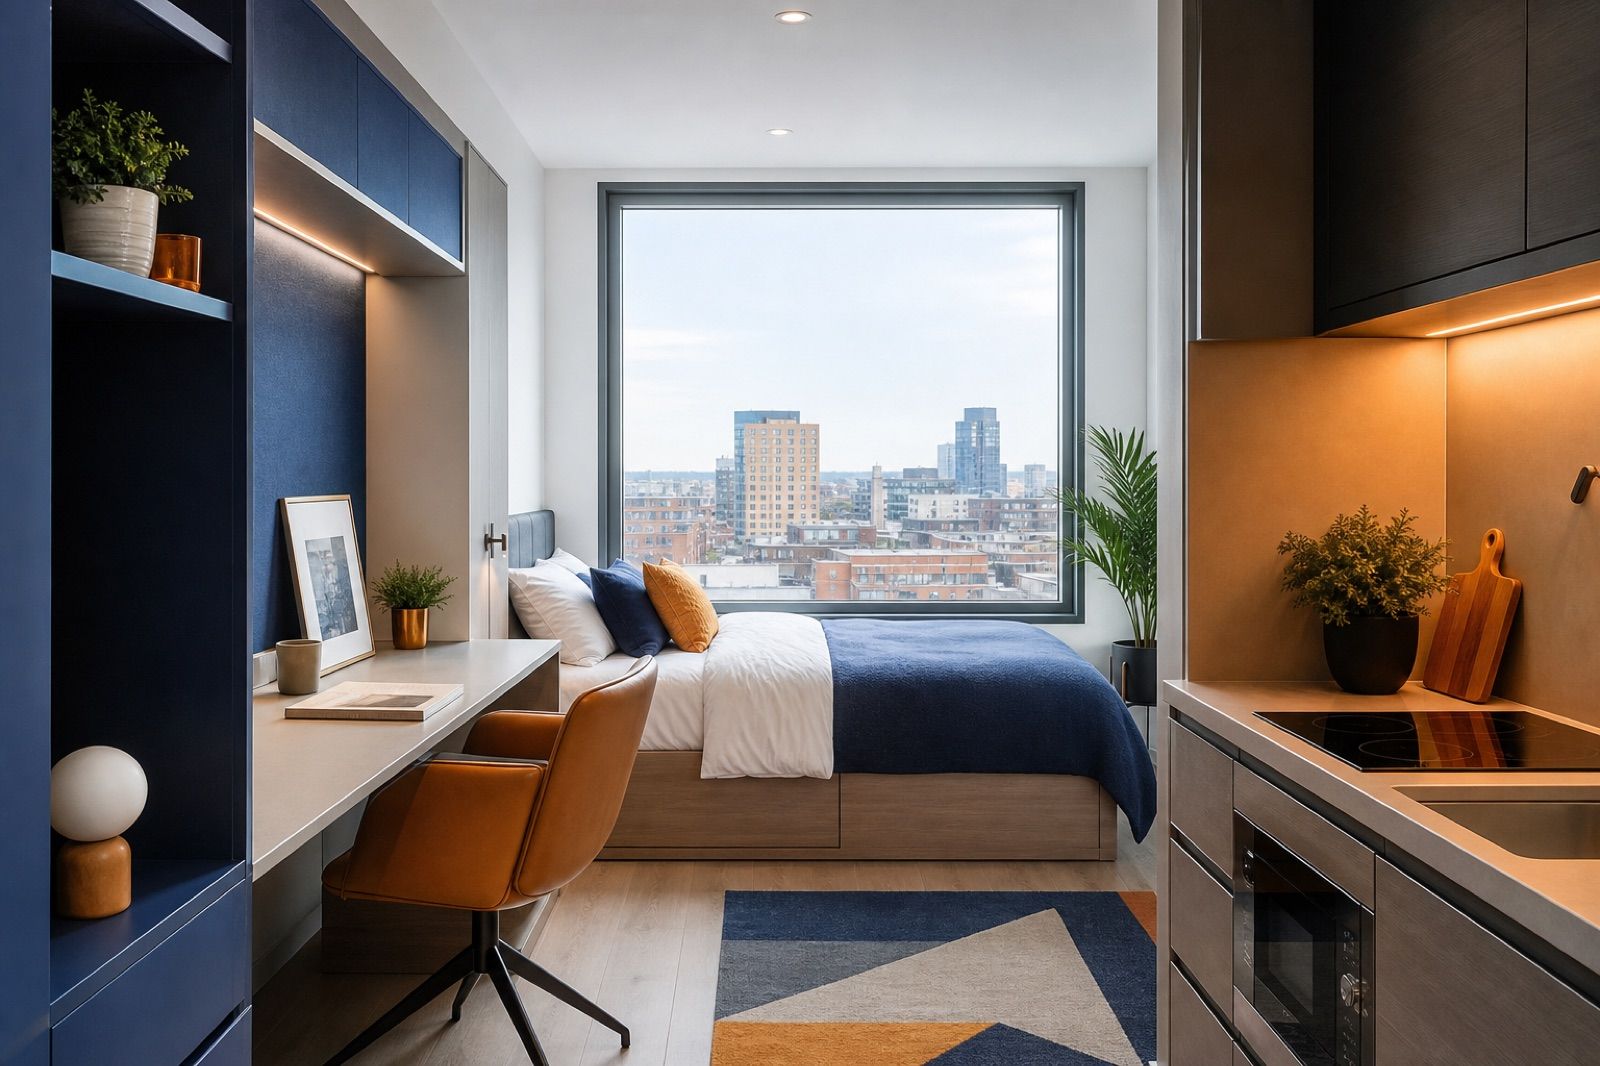
A student studio is a self-contained unit with its own bedroom, study space, kitchenette and en-suite bathroom, let to a single student. It is the premium, direct-let end of purpose-built student accommodation, commanding the highest rents per bed and appealing to postgraduate and international students who want privacy rather than the shared kitchen of a cluster flat.
Studio finance, as we use the term, is the development, investment or commercial mortgage facility used to build, buy or refinance student studios as an income-producing asset. That covers a whole studio-led PBSA block held by one owner and, separately, individual studios sold off on long leases to private investors, which are financed very differently from a single asset.
The financing question hinges on whether the studios are held as one scheme or as fragmented leasehold units. A whole scheme is underwritten on its operator, occupancy and loan to value much like any PBSA asset. An individually titled studio is a smaller, more specialist lend where leasehold terms, ground rent, the management structure and resale liquidity all weigh on lender appetite.
We present the asset, the lease structure and the income so lenders can price it, and we run the market across PBSA investment lenders and the specialist funders who consider individual studio units.
What we fund
- Whole studio-led PBSA schemes held by a single owner
- Studio blocks with concierge and shared amenity
- Individually titled leasehold studios for private investors
- Mixed schemes with a premium studio element
- Postgraduate and international student studio product
- Standing studio assets being refinanced or repositioned
Financing student studio investments
We arrange studio finance in two distinct ways depending on how the asset is held. For a whole studio-led scheme we place an investment loan or commercial mortgage to around 60 to 70% of value over three to seven years, underwritten on the operator, occupancy and rental income, or development finance to about 60 to 70% of loan to cost to build it. For an individually titled studio bought on a long lease, appetite is narrower: a smaller pool of specialist lenders considers these, often at a lower loan to value, with close attention to the lease length, ground rent, the management company and how readily the unit could be resold. We frame every figure as indicative and never as an offer; the terms depend on the asset, the tenure and the operator.
Mortgageability and lender appetite for individual studios
A whole studio scheme is widely banked by PBSA investment lenders, Shawbrook, Secure Trust Bank, Paragon Bank, OakNorth and Allica among those active on stabilised student assets. Naming a lender describes the market; it does not mean we have a relationship with it. An individual leasehold studio is a different proposition. Many mainstream lenders decline single studio units because they are hard to value and resell, so the field narrows to specialist commercial lenders who price the lease, ground rent and management structure carefully. As an arranger with no exclusive tie, we are candid about which studios are readily financeable and which are not, and we take the case to the lenders genuinely comfortable with the tenure rather than chasing ones that are not.
Yields, leases and the studio resale market
Studios sit at the premium end of the student market on rent per bed, but Knight Frank found the most expensive stock cooling fastest in 2025/26, with private direct-let studio rents slightly down on the year (Knight Frank, 2025/26), so the rent a studio can hold matters more than its peak. For finance, the swing factor on an individual studio is liquidity. Fragmented leasehold units can be slower to resell than a whole scheme, which is why lenders weigh the lease length, ground rent and management arrangements when sizing a loan and an exit. A well-located whole studio scheme with a credible operator refinances or sells much like any prime PBSA asset, with prime direct-let yields of around 4.75% in London and 5.50 to 5.75% regionally (Knight Frank, Q2 2026).
Finance that suits studios
- PBSA acquisition and investment financeBuys a whole studio-led scheme as an income asset.
- PBSA investment term loansLong-term debt on a stabilised studio scheme.
- PBSA development financeFunds construction of a new studio-led block.
- PBSA refinanceRe-prices debt or releases equity from a standing studio asset.
What drives a student studio's numbers
Studios earn the highest rent per bed in student accommodation, but the economics split sharply by how the asset is held. A whole studio scheme behaves like any PBSA asset, valued on occupancy, rental income and operator. Knight Frank found the most expensive stock cooling fastest in 2025/26, with private direct-let studio rents slightly down on the year (Knight Frank, 2025/26), so we test the rent a scheme can hold, not the rent it achieved at the peak. An individually titled studio is a different calculation: the lease length, ground rent, management charges and resale liquidity weigh as heavily as the rent, because the buyer pool is small and many lenders decline single units. We model the net income after management and ground rent, and we are clear-eyed about liquidity, because that is what a lender prices when sizing a loan and an exit on a fragmented studio.
Indicative studio leverage and rates
Indicatively we arrange whole studio schemes on an investment loan or commercial mortgage to around 60 to 70% of value, or development finance to about 60 to 70% of loan to cost to build them, on terms comparable to wider PBSA. Individual leasehold studios attract narrower, more specialist appetite, often at a lower loan to value, with lenders pricing the lease, ground rent and resale liquidity carefully. Prime direct-let PBSA yields of around 4.75% in London and 5.50 to 5.75% regionally (Knight Frank, Q2 2026) anchor whole-scheme value, while individual studios often quote higher headline yields to reflect weaker liquidity. These are market-typical, indicative figures and never an offer; the terms depend on the asset and its tenure, and we run the market accordingly.
