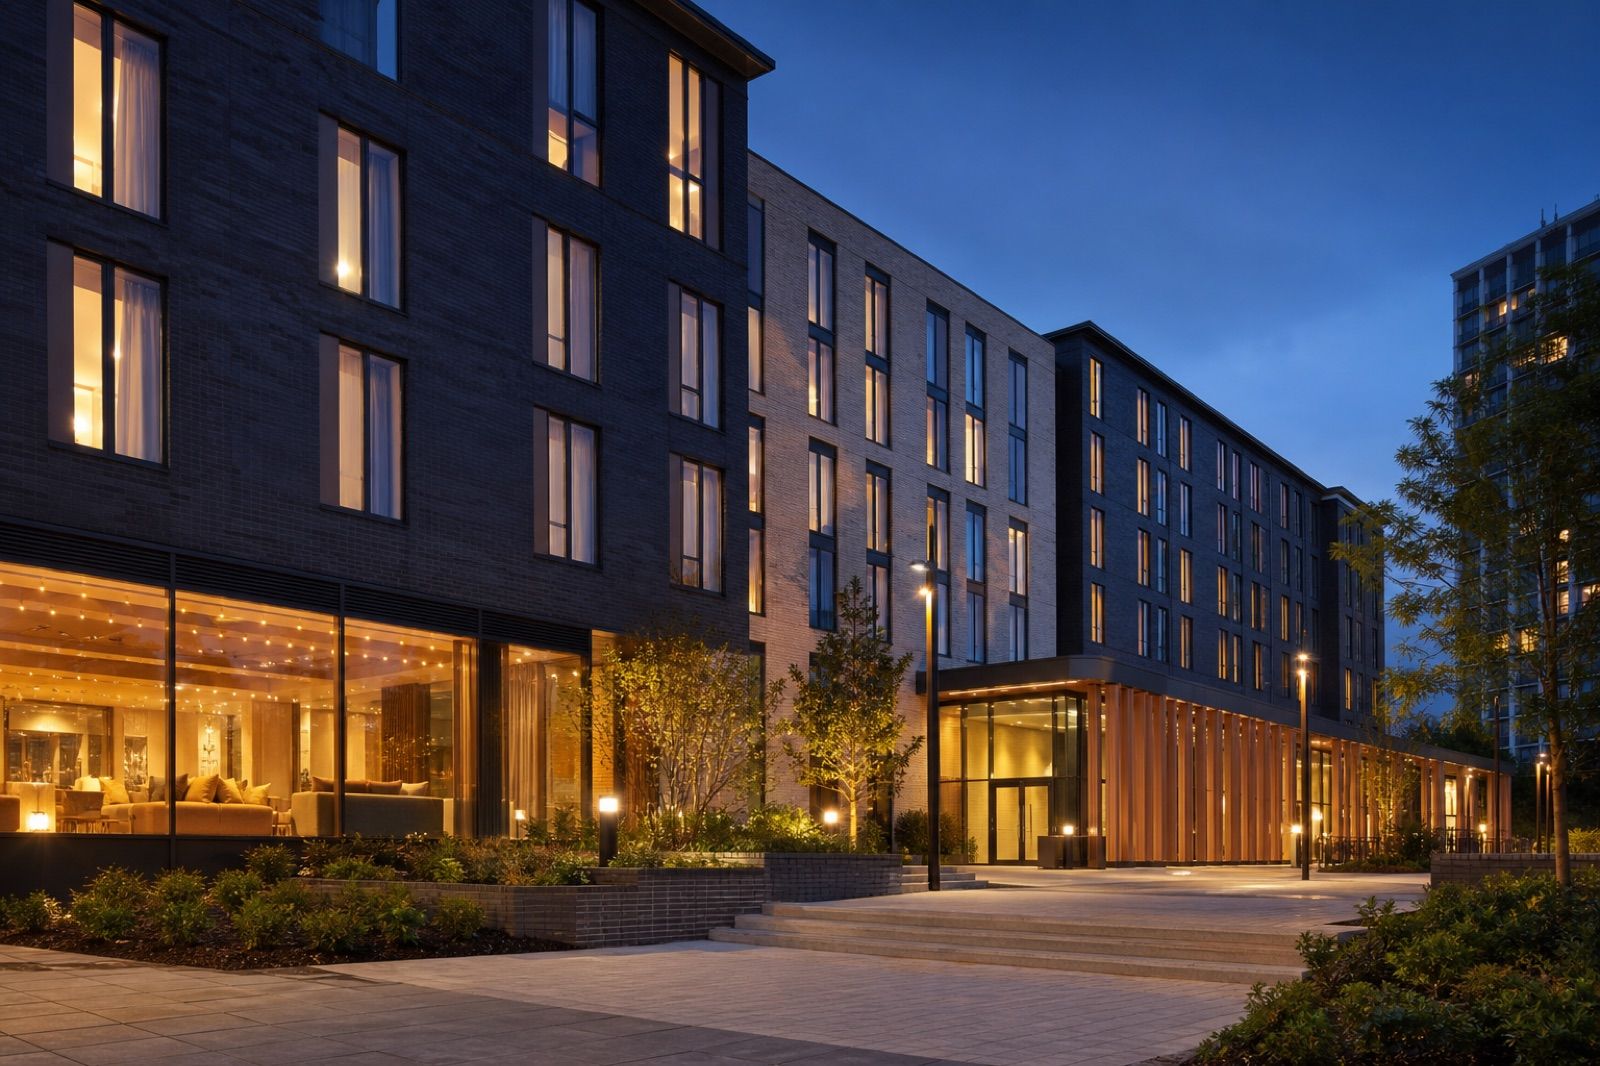
What is PBSA?
PBSA stands for purpose-built student accommodation: residential buildings designed, built and operated specifically for students, let by the bed or the studio on academic-year tenancies, usually with on-site management, bills included and shared amenity space. In real estate, PBSA is an operational asset class valued on its income, occupancy and operator rather than on vacant-possession bricks and mortar.
The term separates purpose-built stock from the traditional student house in multiple occupation (HMO), a converted family home let room by room. PBSA ranges from single city-centre blocks of a hundred or so beds to towers and campus-adjacent schemes of a thousand beds or more, and from privately operated direct-let buildings to schemes let to a university under a nomination agreement.
UK higher education had 2,863,180 student enrolments in 2024/25 (HESA), and Knight Frank values the professionally managed student accommodation market at £84.8bn (Knight Frank, 2026), which is why investors and lenders treat PBSA as a mainstream institutional asset.
| PBSA | Student HMO | |
|---|---|---|
| What it is | Purpose-built block let by the bed or studio | Converted house let room by room |
| Formats | Studios and en-suite cluster flats | Shared house, shared bathrooms or en-suites |
| Management | On-site operator, amenities, bills included | Landlord or letting agent |
| How it is valued | Income and yield, operator and occupancy | Mainly bricks and mortar, sometimes investment value |
| Typical finance | Development, forward funding, investment debt | HMO buy-to-let and portfolio mortgages |
Funding pbsa
Purpose-built student accommodation, or PBSA, is residential property designed and operated specifically for students and let by the bed or the studio. It spans high-rise city schemes, campus-adjacent blocks and standing portfolios, and divides broadly into self-contained studios and shared cluster flats. It is now an institutional asset class in its own right, distinct from the student house in multiple occupation that preceded it.
PBSA finance, as we use the term, is the development, forward-funding, bridging, stabilisation, investment term or refinance facility used to build, acquire, stabilise or hold a PBSA scheme as an income-producing property asset. The decision turns on the location, the depth of university enrolment in the catchment, the operator, the unit mix and the loan to cost or loan to value, not on any one borrower's personal income.
Lenders read PBSA through its operational fundamentals. New supply has run below its long-run pace, with around 19,000 beds under construction for 2026/27 against a ten-year average of about 21,000 a year (Knight Frank, Q2 2026), while rental growth has cooled to 2% in 2025/26 (Knight Frank) and occupancy has softened in some regional cities. Reading that balance city by city is what gives senior lenders and institutional investors confidence to fund the asset across its lifecycle.
We package the scheme, the operator and the numbers so that PBSA-experienced lenders and funders can price each stage quickly, and we run the market across development, forward-funding, bridging, stabilisation and investment debt rather than approaching a single bank.
What we fund
- Studio-led direct-let PBSA schemes
- Cluster-flat PBSA with en-suite bedrooms and shared kitchens
- Mixed studio and cluster PBSA blocks
- Campus-adjacent and city-centre PBSA towers
- Schemes let to a university under a nomination agreement
- Standing, income-producing PBSA portfolios
How we arrange PBSA finance across the lifecycle
We arrange finance at every stage of a PBSA scheme and structure the route from one stage to the next. For a build we place development finance to around 60 to 70% of loan to cost, or roughly 60 to 65% of GDV, with the construction drawn against a monitoring surveyor. Where an investor commits ahead of practical completion we arrange forward funding so construction is funded in stages and the asset is taken on completion. Once a scheme completes but is still leasing up we arrange short-dated stabilisation finance, then place an investment term loan to around 60 to 70% of value over three to seven years once occupancy and income are proven. Bridging covers site acquisition, planning gain or a fast purchase ahead of a term facility. We frame every figure as indicative and never as an offer; the terms a scheme attracts depend on its location, operator, lease structure and trading.
What lenders assess and who funds PBSA
Lenders underwrite PBSA on location, the depth and direction of university enrolment in the catchment, the operator and the unit mix, then size against loan to cost or loan to value. Shawbrook, Secure Trust Bank, Paragon Bank and Puma Property Finance are active across PBSA development and investment lending, with Together, InterBay and Alternative Bridging appearing on bridging and shorter-dated work, and OakNorth and Allica on stabilised investment debt. Naming a lender describes the market; it does not mean we have a relationship with it. Institutional funders and the listed operators, Unite Students and iQ Student Accommodation among them, set the tone for the prime end of the market. As an arranger with no exclusive tie, we test the scheme, the operator covenant and the income basis, whether direct let or nomination, against the lenders and funders most likely to price it keenly, rather than steering every case to one name.
Why PBSA is an institutional asset class
The investment case behind PBSA lending is deep and well evidenced. Investors committed £4.3bn to UK PBSA across 79 deals in 2025 (Knight Frank), and Knight Frank values the professionally managed market at £84.8bn (Knight Frank, 2026), a deep and liquid market. The cycle has turned, though: the CBRE UK PBSA Index returned 3.4% in the year to September 2025, a 5.4% income return offset by a 2.0% fall in capital values (CBRE), rental growth slowed to 2% in 2025/26 from an 8.3% peak (Knight Frank), and prime direct-let yields of around 4.75% in London and 5.50 to 5.75% regionally (Knight Frank, Q2 2026). For lenders and investors, a well-located scheme with a credible operator is both a resilient income asset and a clear exit, whether by refinance or sale.
Finance that suits pbsa
- PBSA development financeFunds ground-up construction of a PBSA scheme, drawn against cost.
- Forward funding and forward commitmentFunds construction in stages for an investor taking the asset on completion.
- PBSA stabilisation financeBridges the lease-up period from completion to proven occupancy.
- PBSA investment term loansLong-term debt on a stabilised, income-producing scheme.
What drives a PBSA scheme's numbers
A PBSA scheme's value to a lender comes down to location, university enrolment in the catchment, the operator and the income its beds produce. The market backdrop has cooled: average PBSA rental growth slowed to 2% in 2025/26 from a peak of 8.3% (Knight Frank, 2025/26), and occupancy has softened in some regional cities where new supply landed, even as UK HE enrolments held at 2,863,180 in 2024/25 (HESA). The decisive variables are the depth and direction of enrolment in the catchment, the unit mix between studios and cluster beds, and whether income is direct let or contracted under a nomination. We model the maintainable net income a scheme will produce, not a single strong cycle, because that is what a development lender capitalises into GDV and an investment lender lends against.
Indicative PBSA leverage across the lifecycle
Indicatively we arrange PBSA development finance to around 60 to 70% of loan to cost, or roughly 60 to 65% of GDV, with construction drawn against a monitoring surveyor. Forward funding lets an investor commit pre-completion and fund the build in stages. Stabilisation finance carries a completed scheme through lease-up, after which an investment term loan sits at around 60 to 70% of value over three to seven years, with the keener loan to value reserved for prime locations, strong operators and contracted income. Prime direct-let net initial yields of around 4.75% in London and 5.50 to 5.75% regionally (Knight Frank, Q2 2026) set the investment value. These are market-typical, indicative figures and never an offer; the terms depend on the scheme, the operator and the catchment, and we run the market to find them.
